
I think for most of us, retirement is a goal we think about a lot, especially as we enter late middle age. After decades of working, the grind starts to get us down, and we dream of free days, travel, time spent on hobbies or with family, and being answerable to no one but ourselves.
Too bad it’s out of reach for so many Americans.
According to the Federal Reserve’s Survey of Consumer Finances and NerdWallet, the average savings of Americans who have a retirement account by age is:
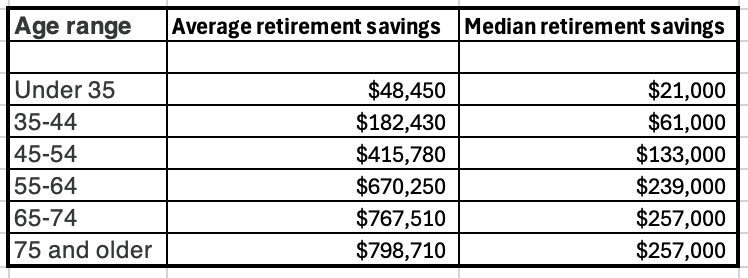
But there are some caveats:
- These figures only account for those with a dedicated retirement account such as a 401K or an IRA. This means approximately 46% of Americans are excluded. When you include all Americans, the average drops to $955 across all age groups.
- There’s also the fact that the richy-rich skew the averages on these numbers. only 9.3% of all U.S. Hold-holds have $500,000 or more, and only 5% of households have $1M or more.
- That leaves 85.7% of households with less than $500K in retirement savings, most with considerably less.
According to Fidelity Investments, people should save ~15% of their pretax income each year for retirement, which makes sense if you’re simply crunching the numbers with no consideration for other factors. I plugged a prompt into Gemini to determine what someone would have after 40 years of saving 15% if they start with an annual salary of $40,000, receive a 3% raise each year, and have returns of 6% each year on their savings. The number ends up being $1,404,736.03. Absolutely better than the average and median, but then things like life happen.
Here in the Denver metro area, the average salary is ~$80,000, since we’re a high cost of living area. Zillow reports that the average rent for an apartment is $1,950. An average single family home sells for $645,000, with multi-family homes selling for $375,000. Using the standard 28% benchmark, this means someone with a $80,000 salary can afford a home which costs $240,000 to $360,000 plus insurance, HOA fees, etc. That prices half the population right out of ownership, and really, even renting becomes problematic. When you add in life events like, I don’t know, having children, or paying for taxes, healthcare, childcare, food, transportation, utilities, etc., there’s not much left to save for retirement.
And that’s for the average salary. I have no idea how the bottom quartile manages to make ends meet, let alone save for emergencies or retirement. I guess they’re supposed to work until they drop dead from exhaustion, or old age, or an illness they can’t afford to treat, which is just fucked up beyond belief.
Now, to be honest, the Smart Man and I are very, very lucky. We’re both White and CIS, we gained skills in the Armed Forces which translated well into civilian life, we worked hard, we’re bright, and we both had smart mothers who insisted we get civilian jobs that subsidized our health insurance and 401K retirement plans. I was fortunate to be in the right place at the right time with the right skills to get into technical sales, where I was able to bring home far more than I would have otherwise. And I also believe it was easier in the 90s and aughts to get ahead without a college degree.
I think it’s harder for Millennials. The tech-bro oligarchy and the wealth gap has done nothing but increase in power and size since the Reagan years, and it seems that Millennials have to start off pretty well off (and without student debt) before they can even consider getting wealthy. And I mean wealthy in the “I have over a million dollars in the bank” wealthy, not the richy-rich rich wealthy.
Social Security is supposed to close some of this gap, but with the current demographics of our country and the government cutting benefits in order to give the military industrial complex more and better contracts and their richy-rich rich friends tax cuts so they can buy their third yacht, I really don’t see how Social Security is sustainable. The Smart Man and I have projected our retirement spending to exclude Social Security to be on the safe side, but folks who rely on unskilled labor jobs or lower paying service jobs don’t have that luxury.
So what do we do? Let the olds die in the streets while Zuckerberg, Musk, Alton, Bezos and Thiel invite them to eat cake? Or do we encourage our new Democratic Congress to get off their asses and do something about income inequality? I know which way I’m going, and I’m already composing my first letter to my new Representative, RADM Eileen Labaucher, even though the race hasn’t technically been called.



 Posts


0 comments:
Post a Comment